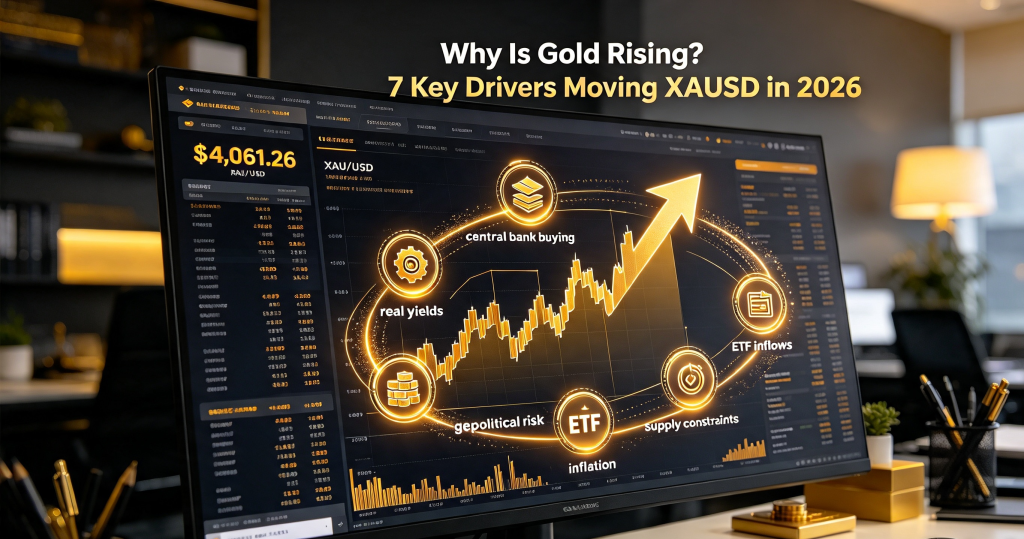
Gold has been on a remarkable ascent in 2026, repeatedly setting fresh all-time highs and capturing the attention of traders, investors, and central banks worldwide. The XAUUSD pair — gold priced against the US dollar — has surged to levels few analysts predicted just a year ago, driven not by one single catalyst but by a powerful combination of structural shifts, monetary policy changes, and global rebalancing. Below are the seven key drivers behind gold’s rally and what they mean for your trading and investment decisions.
Replace with your AdSense code in functions.php or via filter
1. Falling US Real Yields & Federal Reserve Policy
The single most influential factor steering gold in 2026 is the trajectory of real interest rates — nominal Treasury yields minus inflation. Because gold pays no interest or dividends, it becomes significantly more attractive when inflation-adjusted returns on bonds decline.
Throughout 2026, market expectations have shifted toward a slower-than-expected pace of rate cuts, yet the broader trend remains supportive: sticky core inflation above the Federal Reserve’s 2% target keeps real yields suppressed, eroding the purchasing power of fixed-income assets. When the Fed signals a pivot toward easing — or even just pauses further hikes — gold rallies. Conversely, hawkish surprises can trigger sharp pullbacks. This relationship is the backbone of every serious XAUUSD analysis.
2. Central Bank Buying at Record Levels
Never before have the world’s central banks accumulated gold at the pace seen since late 2025 and into 2026. Driven by de-dollarisation, geopolitical diversification, and a desire to reduce reliance on G7 reserve assets, official institutions have become the single most consistent source of structural demand.
Emerging-market nations — led by China, India, Russia, and several Eastern European economies — are leading the charge. Purchases averaged more than 50 tonnes per month through much of 2026, with peaks exceeding 100 tonnes in June alone. Unlike speculative flows that vanish when sentiment shifts, central bank buying provides a durable floor under prices and fundamentally alters the supply-demand balance for years to come.
3. US Dollar Weakness & Fiscal Sustainability Concerns
Gold and the US dollar share an inverse relationship: when the dollar weakens, gold becomes cheaper for holders of other currencies, lifting global demand and pricing. In 2026, the greenback has faced persistent pressure from swelling fiscal deficits, slowing relative growth, and the gradual international diversification away from USD-denominated reserves.
The US fiscal outlook — with debt-to-GDP ratios marching higher and no credible long-term consolidation plan — has prompted institutional investors to reassess the dollar’s role as the sole anchor of stability. Gold, as a neutral, borderless asset with no counterparty liability, naturally benefits from this re-evaluation.
4. Geopolitical Fragmentation & Heightened Risk
From unresolved regional conflicts to trade realignments and the emergence of new economic blocs, 2026 has been defined by geopolitical fragmentation. In such an environment, gold serves as the ultimate safe haven — it cannot be frozen, sanctioned, or devalued by any single government.
Periods of elevated uncertainty trigger two distinct flows: immediate flight-to-safety buying that spikes prices rapidly, followed by longer-term portfolio reallocation as institutions permanently increase gold allocations. Even when tensions temporarily ease, the structural reassessment of risk keeps gold well supported compared to previous decades.
5. Persistent Inflation & Currency Debasement Fears
For years, investors treated inflation as transitory. In 2026, the narrative has shifted: price pressures have proven stickier than forecast across major economies, particularly in services and energy sectors. Gold, historically the premier inflation hedge, has regained its status as a portfolio shield against eroding purchasing power.
Crucially, it is not just current inflation but the fear of future currency debasement that drives accumulation. With government debt levels at multi-decade highs across the developed world, markets anticipate that policymakers will ultimately tolerate higher inflation to inflate away nominal obligations — a scenario that favours hard assets like gold over fiat currency.
6. Investment Demand Surge: ETFs & Institutional Allocation
Gold is no longer just a physical commodity or jewellery purchase — it has become a mainstream tradable asset via exchange-traded funds (ETFs). Through mid-2026, global gold ETFs attracted more than $77 billion in net inflows, with Europe and North America leading the wave.
This surge is not speculative day-trading alone: pension funds and asset managers are lifting strategic allocations from traditional 1–2% ranges toward 3–5% and higher. Once these large capital pools commit, they tend to stay invested, creating sustained upward momentum that short-term news alone cannot easily reverse.
7. Supply Constraints & Production Realities
For all the soaring demand, gold supply remains stubbornly inelastic. Major mining projects take 5–10 years to move from discovery to production, and environmental permitting plus capital costs have risen sharply. Even at elevated prices, annual output growth rarely exceeds 1–2% — meaning supply simply cannot keep pace when investment demand doubles or triples.
This inelasticity amplifies price moves: a relatively modest increase in capital flows can generate outsized percentage gains because there is no flood of new supply to satisfy demand quickly. When central banks, institutions, and retail buyers all compete for essentially flat annual output, the result is a structural imbalance that favours higher equilibrium prices over time.
What This Means for Traders & Investors
Understanding these seven drivers is one thing — applying them is another. Here is the practical takeaway:
- For day traders: Watch real yields and the USD index (DXY) before every major news release. Gold often moves $20–$50 within minutes of Fed communications or CPI data.
- For swing traders: Geopolitical escalation and central bank purchase announcements provide multi-day trends. Check the World Gold Council and LBMA reports monthly for flow confirmation.
- For long-term investors: The combination of fiscal deficits, de-dollarisation, and suppressed real yields creates a multi-year constructive backdrop. Pullbacks are historically where patient buyers accumulate positions.
- The risk to this thesis: If inflation collapses rapidly and the Fed returns to aggressive hiking, real yields could spike — pressuring gold. But that scenario appears increasingly unlikely as 2026 unfolds.
Final Thought
Gold’s rise in 2026 is not a speculative bubble — it is a price adjustment to a fundamentally different financial reality. The interplay of monetary policy rethinking, de-dollarisation, persistent inflation, and supply constraints has rewritten the rules of engagement for XAUUSD. The trend is firmly upward, but the path will remain volatile. Respect the drivers, manage your leverage, and let the fundamentals guide your decisions.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Always conduct your own research before trading or investing. Past performance is not indicative of future results.

Leave a Reply